

Thrift Savings Plan
4.8

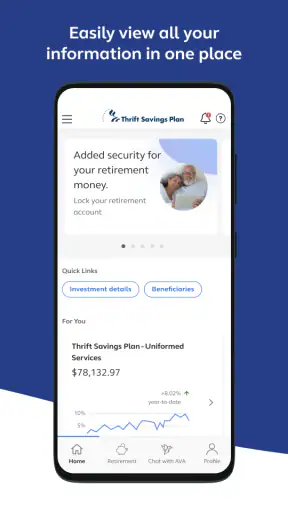
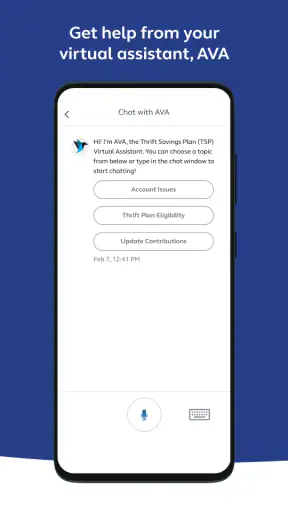
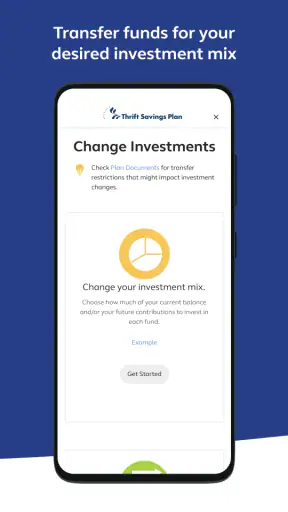
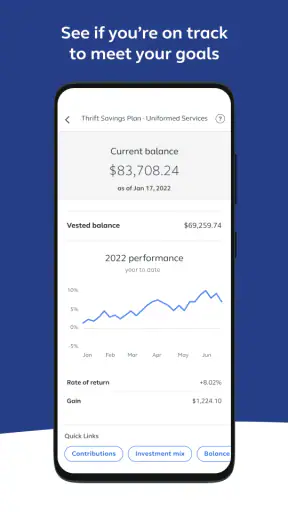
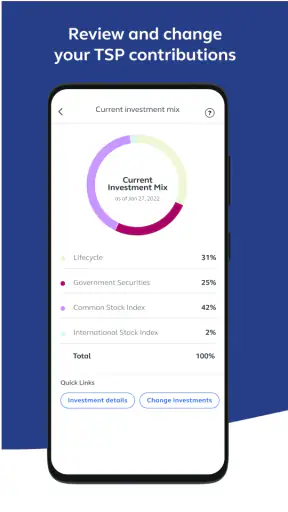
Managing retirement savings is rarely something I want to do in a hurry, and that is why I found the Thrift Savings Plan app more useful than its short store description suggests. It is a free business app from FRTIB that puts my Thrift Savings Plan account on a phone instead of making every check require a browser, a desktop, or a call. I used it as a focused account-management tool rather than as a general investing app, and that distinction matters from the first tap.
Thrift Savings Plan is best for people who already use the TSP and want a more direct way to check or manage their plan while away from a computer. It is not designed to replace a full personal-finance dashboard, a market-news service, or an educational investing platform. Its value comes from keeping the essential TSP relationship close at hand, with less visual and mental clutter than a broad financial app can create.
How the app feels to use in different situations
Readability and navigation that keep the task focused
My first impression was that the app feels purpose-built. Instead of asking me to sort through unrelated accounts, cards, loans, budgets, and promotions, it keeps attention on the Thrift Savings Plan. That narrow scope is a real advantage when I only want to review my retirement account or complete a plan-related task. A focused interface can reduce the chance of opening the wrong financial product, especially when I am checking something quickly.
The app’s role is also easy to understand. FRTIB is the developer, and the product is clearly tied to the TSP rather than presented as an independent financial service that happens to display retirement information. That clarity helps establish the right expectation: I am opening an account-management channel, not a tool that will compare every investment option in my financial life.
For readability, I would approach the app with the same care I use for any financial screen. Account balances, contribution details, and transaction-related information deserve a slower read than a casual notification. On a phone, figures can feel more compressed than they do on a large monitor, and a user who enlarges system text or relies on strong visual contrast may find that some screens require extra checking. The app is convenient, but convenience should not turn into hurried confirmation of an important change.
One practical habit helped me: I decide what I want to do before opening the app. If I am only checking a balance, I avoid wandering through other areas. If I am reviewing a contribution or allocation decision, I pause after each screen and reread the labels. This simple workflow makes the app feel calmer and is especially helpful for anyone who finds dense financial information tiring.
The current version is 7.2.0, and the app requires iOS or Android 12 or later. That operating-system requirement is worth checking before downloading, particularly on an older phone that still works well for everyday communication. A newer app can be perfectly usable on a supported device while remaining unavailable to someone who cannot update their operating system.
Motor and sensory considerations during account tasks
Phone-based account access can be easier than a desktop for some people and harder for others. I can hold the device close, use it from a comfortable chair, and complete a short check without setting up a workstation. That flexibility may help users with limited stamina or people who need to change posture frequently. It also makes the app practical for a quick review during a break, provided the surroundings are private.
At the same time, small touch targets and scrolling can create friction for users with tremors, reduced dexterity, or difficulty maintaining precise finger placement. Financial actions are not a good place for accidental taps, so I would avoid using the app while walking, riding in a moving vehicle, or carrying something in the other hand. A stable surface and a few uninterrupted minutes make a meaningful difference.
Voice interaction and device-level accessibility settings can sometimes make mobile apps easier to operate, but the experience may depend on how each screen exposes its labels and controls. I would not assume that every element will behave identically with a screen reader, magnification, switch access, or a custom display setting. Anyone who depends on one of these tools should test the key actions first, rather than waiting until an urgent account task is needed.
Color perception is another consideration. Retirement information often uses visual grouping to separate categories or status indicators, yet color alone should never be the only clue a person relies on when interpreting a financial screen. If a label, number, or action is unclear, I would rotate the phone, increase display contrast where available, or move to a larger screen before making a decision. The app’s focused design helps, but it cannot remove the limitations of a small display.
Audio sensitivity and attention also affect the experience. A phone may produce interruptions from other apps, calls, or notifications while I am reviewing private information. I prefer a quiet setting with nonessential alerts muted. This is not just about comfort: fewer interruptions reduce the chance of losing my place or confirming something without fully reading it.
Situational access beyond the home
The strongest everyday use case is a short, intentional check. For example, I might receive a reminder to review my retirement contribution, sit down before work, sign in, verify the relevant information, and close the app without opening a laptop. That workflow is more realistic for many people than scheduling a long desktop session. The phone becomes a practical access point rather than another complicated financial system.
It can also help someone who travels frequently or shares a computer with family members. A personal phone offers a more private route to an account than a public or shared browser. I still would not use it on an open network or in a crowded place where another person can see the screen. The fact that an app is mobile does not make a sensitive financial task automatically private.
For users with limited internet access, the important question is not whether the app is installed but whether the intended task can be completed reliably in the moment. I would plan around a dependable connection and avoid leaving an important account change until the last minute. A phone can be more available than a computer, but it is still affected by signal quality, battery life, and interruptions.
The app is also relevant for people who find websites visually overwhelming. A dedicated mobile experience can reduce the number of competing menus and browser elements. That may benefit users with attention-related difficulties or anyone who loses track of a task when too many links are visible. However, a smaller screen can reverse that advantage if the user needs to compare several pieces of information at once.
That trade-off is why I see the app and the usual desktop website as complementary rather than interchangeable. I prefer the app for a focused check or a straightforward account action. I would choose a larger screen when I need to read several details side by side, keep reference material open, or take time to review a complicated decision. The better option depends less on loyalty to one platform and more on the user’s visual, motor, and concentration needs.
Where the app still creates barriers
The biggest limitation is the narrow purpose of the product. Someone looking for a complete picture of savings, banking, debt, taxes, and other investments will still need separate tools. The app can help manage the TSP, but it does not become a universal financial workspace simply because it is on a phone. Users who want automatic aggregation across providers may prefer a broader personal-finance service, while accepting that those services are not the same as using a plan-specific channel.
Another barrier is the age requirement for the operating system. Requiring Android or iOS 12 and later keeps the app aligned with relatively modern devices, but it can exclude people who cannot afford a replacement phone or who rely on an older device for accessibility reasons. This is particularly important for users who have carefully configured an older phone with familiar text size, input methods, or assistive settings.
Sign-in and account security can also be a point of friction. I consider that friction justified for retirement information, but it may be tiring for users with memory difficulties, limited hand control, or unreliable access to another verification step. A secure process is only truly practical when the person can complete it without confusion. I recommend setting aside time for the first login and keeping any required account-recovery information in a safe, accessible place.
Mobile privacy presents a different kind of barrier. A person may need help from a family member or caregiver to navigate the app, yet account information is sensitive and should not be casually exposed. If assistance is necessary, I would have the account holder remain involved, use a private setting, and avoid sharing credentials. The app’s convenience should support independence, not encourage unsafe delegation.
There is also a cognitive trade-off in having important retirement actions available so quickly. Easy access is useful, but it can make a user feel pressured to act before understanding a choice. I treat the app as a place to review and carry out a decision I have already considered, not as a reason to make an impulsive change. For complex questions, a larger screen or direct support may be more appropriate than trying to interpret everything on a phone.
Who will benefit most from this focused TSP access?
I would recommend it first to an existing TSP participant who wants a convenient mobile route to plan information and account management. It is especially suitable for people who dislike navigating a general finance app and prefer a tool dedicated to one retirement plan. The free price removes a common barrier, and the Everyone content rating makes it broadly suitable from a store-classification perspective.
The app has also built a substantial user base, with over 500 thousand installs, a 4.8 average from around 5.5 thousand ratings, and around 1.9 thousand written reviews. Those figures suggest that the focused approach resonates with many people, although popularity does not guarantee that every screen will suit every accessibility setup or device.
I would be more cautious about recommending it as the only financial app for someone who needs cross-account budgeting, investment comparison, or detailed planning tools. It is also not my first choice for a user who does most financial work on a large monitor or who needs to compare long, information-heavy screens. In those cases, the conventional web experience or a broader financial tool may be easier to inspect, while the app remains useful for quick checks.
People with older phones should check compatibility before planning around it. Users who depend on assistive technology should test the actions they actually need: signing in, locating account information, reading the important values, and completing a change if that is part of their routine. A product can be well designed in general and still have a particular control that does not cooperate with an individual setup.
My practical approach to using it
I would begin by using the app for observation rather than immediate changes. Open it when there is enough time, confirm that the text and controls are comfortable, and learn where the information you regularly need is located. This first session is a good opportunity to discover whether the phone’s screen size, display settings, and input method work for you.
For recurring checks, I would create a personal routine: use a stable surface, choose a private location, silence interruptions, and read each important value twice before leaving the screen. If I need to make a contribution or allocation decision, I would review the decision outside the app first and use the app only for the final account task. That separation reduces pressure and makes errors less likely.
I would also keep the desktop alternative available. If a screen feels cramped, a label is difficult to interpret, or I need to compare multiple details, switching devices is not a failure of the app. It is the sensible response to the limits of mobile viewing. The best accessibility strategy here is flexibility: use the phone for convenience, and use a larger interface when clarity matters more than speed.
Finally, I would avoid judging the app only by how quickly it opens or how few taps a task takes. For retirement savings, a clear pause is valuable. The app succeeds when it gives me a manageable path to the TSP without distracting me, but responsible use still requires attention, privacy, and enough time to understand what I am confirming.
An inclusive verdict for everyday TSP management
After using it as a dedicated retirement-account companion, I see Thrift Savings Plan as a practical option for people who want focused mobile access rather than a full financial command center. Its strongest quality is its narrow purpose: it keeps the TSP close without surrounding the task with unrelated money tools. That can support readability, attention, and independence in everyday situations.
Its inclusive value is more nuanced. A phone can be easier to hold, easier to access, and less intimidating than a desktop, but small controls, device compatibility, sign-in friction, privacy concerns, and assistive-technology differences still matter. I would recommend testing the app in the exact context in which it will be used, especially if the user has motor, visual, cognitive, or sensory needs.
My final view is positive, with clear boundaries. If you already manage a TSP and want a free, plan-specific app for focused checks and account tasks, this is a sensible download to try. If you need broad financial planning, extensive comparison, or a larger reading area, pair it with the usual desktop or personal-finance alternatives instead of expecting one mobile app to do everything. The best reason to choose it is controlled, convenient access to your TSP—not a replacement for every financial tool you use.
4.8
1.91K Reviews
Pros
- Official source for managing federal employee retirement savings
- Supports checking balances
- contributions
- and account activity
- Provides access to TSP fund and performance information
- Useful for reviewing interfund transfers and allocation choices
- Secure sign-in helps protect sensitive retirement account details
Cons
- Designed mainly for TSP participants
- limiting its wider usefulness
- Some account actions may redirect to a web-based experience
- Retirement terminology can be confusing for first-time users
- Investment information may feel basic for advanced investors
- Access depends on having an eligible TSP account


